 Bowtie Term Critical Illness (Early Stage & Multiple Cover): Pure Term Multi-Claim AuditVS
 AIA On Your Side Insurance Plan 2 (Whole-Life Multi-Claim CI): 1,100% Cap & Cancer Income Audit
Bowtie Term CI (Early & Multiple) vs. AIA On Your Side Plan 2 (Whole-Life Multi-Claim CI)
Pure renewable multi-claim term CI vs. flagship participating whole-life CI: compare 500% vs. 1,100% total payout caps, 2-year relapse wait vs. 1-year Continuous Cancer Income, 2-tier ICU cover, and premium leverage.
Last verified: 2026-11-20 · Official policy wordings and trustee disclosures always prevail.
Key Takeaways
- Sharply different premium leverage: Bowtie Term CI delivers up to 500% multi-claim cover at HK$105/mo (Age 35 M NS) / HK$169/mo (F NS) per HK$500k, whereas AIA On Your Side 2 requires far higher level premiums to fund whole-life savings.
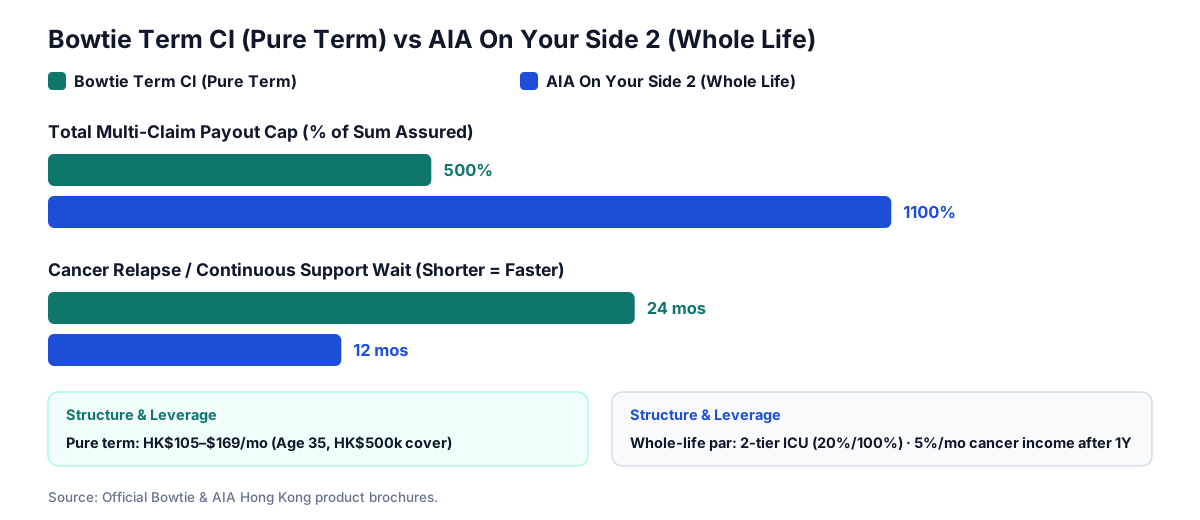
- Cancer wait & ICU depth: AIA offers 1-year-wait Continuous Cancer Income (5%/mo), 2-tier ICU cover (20%/100%), and up to 1,100% total claims; Bowtie uses a 2-year multiple-claim wait up to 500% (reverting to single major at age 86).
- Practical sizing rule: secure 3–5 years of household living expenses via affordable term CI first rather than under-insuring your primary sum assured inside a costly whole-life plan.
Visual Comparison
Clause-by-Clause Matrix
Pure renewable multi-claim term CI with zero savings drag: up to 500% major claims (1st 100% + up to 4 subsequent 100% claims to age 85), 20% early-stage benefit, and published HK$500k NS rates (Age 35: M HK$105/mo, F HK$169/mo).
Flagship Hong Kong participating whole-life multi-claim CI: 115 covered diseases, 10X Multiple CI Benefit up to 1,100% total sum assured, 1-year-wait Continuous Cancer Income option (5%/month), and 2-tier ICU cover.
Earners building high multi-claim cancer, heart attack, and stroke income replacement during peak working years without paying whole-life savings premiums.
Higher-budget households wanting paid-up lifetime CI with 1-year cancer continuous income support and ICU triggers.
Major & Multiple Cover Structure:Covers 42 major illnesses + 4 supplementary coverages (46 items); after 1st Major claim (100%), covers up to 4 subsequent 100% claims up to age 85 for cancer (relapse/metastasis/persistence/new primary), heart attack, or stroke — 500% total. | Waiting Periods & Active Cancer Rule:90-day initial waiting period; 2-year waiting period between Multiple Cover claims, and persistent/recurrent cancer (non-new primary) requires Active Treatment within the preceding 12 months. | Early Stage & Compassionate Death:Early Stage pays 20% of sum insured (capped at HK$300,000 per claim, max 5 claims, 2x allowed for CIS/angioplasty, 2-year wait between early claims); 5% Compassionate Death benefit if no Major claim paid. | Published HK$500k Monthly Rates (Non-Smoker):Age 30: M HK$66 / F HK$90; Age 35: M HK$105 / F HK$169; Age 40: M HK$151 / F HK$280; Age 45: M HK$268 / F HK$404; Age 50: M HK$411 / F HK$521.
Covered Disease Scope:Covers 115 diseases in total: 58 critical illnesses (57 major + 1 minor), 44 early-stage critical illnesses, and 13 severe child diseases. | 10X Multiple CI & Continuous Cancer Income:After 1st major claim (100%), pays up to 10 additional 100% claims to age 85 (up to 1,100% total: Cancer up to 600%, Heart Attack/Stroke up to 300%, Alzheimer's/Parkinson's 100%); Continuous Cancer Income option pays 5%/month after a 1-year waiting period (up to 100 months). | 2-Tier ICU Protection Benefit:Tier 1: ≥72 consecutive hours in ICU advances up to 20% of Initial Sum Assured; Tier 2: ≥120 consecutive hours in ICU with invasive life support alongside complex surgery advances up to 100%. | Fulfillment Ratio Verification:Participating whole-life contract whose long-term surrender value and terminal dividend depend on investment experience; verify AIA Hong Kong's official Fulfillment Ratio & Total Cash Value Ratio disclosures before buying.
Delivers 500% multi-claim cancer/heart/stroke cover at pure term outlay — far lower upfront cost than whole-life participating CI. · Requires insured to be alive on diagnosis date with live medical evidence rather than imposing a 14-day post-diagnosis survival period.
Continuous Cancer Income option cuts cancer relapse/persistence waiting time to 1 year, supporting cash flow during multi-year oncology treatment. · 2-tier ICU triggers provide protection even for severe emergencies or novel illnesses outside named disease definitions.
From Renewal Age 86 onwards, Multiple Cover and Early Stage benefits terminate automatically (only single Major CI + 5% death cover remain), and premiums step up yearly with age. · If a Major CI claim occurs within the 2-year Early Stage waiting period after an Early Stage payout, the Major payout deducts the earlier 20% advancement.
Annual premiums per HK$1M cover are far higher than pure term CI — do not under-insure your core sum assured just to afford whole-life savings. · Steep early surrender losses apply, and the 10X Multiple CI benefit ends at age 85.
| Clause-by-Clause Matrix | Bowtie Term Critical Illness (Early Stage & Multiple Cover): Pure Term Multi-Claim Audit | AIA On Your Side Insurance Plan 2 (Whole-Life Multi-Claim CI): 1,100% Cap & Cancer Income Audit |
|---|---|---|
| Overview | Pure renewable multi-claim term CI with zero savings drag: up to 500% major claims (1st 100% + up to 4 subsequent 100% claims to age 85), 20% early-stage benefit, and published HK$500k NS rates (Age 35: M HK$105/mo, F HK$169/mo). | Flagship Hong Kong participating whole-life multi-claim CI: 115 covered diseases, 10X Multiple CI Benefit up to 1,100% total sum assured, 1-year-wait Continuous Cancer Income option (5%/month), and 2-tier ICU cover. |
| Best Suited For | Earners building high multi-claim cancer, heart attack, and stroke income replacement during peak working years without paying whole-life savings premiums. | Higher-budget households wanting paid-up lifetime CI with 1-year cancer continuous income support and ICU triggers. |
| Verified Clauses & Rates | Major & Multiple Cover Structure:Covers 42 major illnesses + 4 supplementary coverages (46 items); after 1st Major claim (100%), covers up to 4 subsequent 100% claims up to age 85 for cancer (relapse/metastasis/persistence/new primary), heart attack, or stroke — 500% total. | Waiting Periods & Active Cancer Rule:90-day initial waiting period; 2-year waiting period between Multiple Cover claims, and persistent/recurrent cancer (non-new primary) requires Active Treatment within the preceding 12 months. | Early Stage & Compassionate Death:Early Stage pays 20% of sum insured (capped at HK$300,000 per claim, max 5 claims, 2x allowed for CIS/angioplasty, 2-year wait between early claims); 5% Compassionate Death benefit if no Major claim paid. | Published HK$500k Monthly Rates (Non-Smoker):Age 30: M HK$66 / F HK$90; Age 35: M HK$105 / F HK$169; Age 40: M HK$151 / F HK$280; Age 45: M HK$268 / F HK$404; Age 50: M HK$411 / F HK$521. | Covered Disease Scope:Covers 115 diseases in total: 58 critical illnesses (57 major + 1 minor), 44 early-stage critical illnesses, and 13 severe child diseases. | 10X Multiple CI & Continuous Cancer Income:After 1st major claim (100%), pays up to 10 additional 100% claims to age 85 (up to 1,100% total: Cancer up to 600%, Heart Attack/Stroke up to 300%, Alzheimer's/Parkinson's 100%); Continuous Cancer Income option pays 5%/month after a 1-year waiting period (up to 100 months). | 2-Tier ICU Protection Benefit:Tier 1: ≥72 consecutive hours in ICU advances up to 20% of Initial Sum Assured; Tier 2: ≥120 consecutive hours in ICU with invasive life support alongside complex surgery advances up to 100%. | Fulfillment Ratio Verification:Participating whole-life contract whose long-term surrender value and terminal dividend depend on investment experience; verify AIA Hong Kong's official Fulfillment Ratio & Total Cash Value Ratio disclosures before buying. |
| Strengths | Delivers 500% multi-claim cancer/heart/stroke cover at pure term outlay — far lower upfront cost than whole-life participating CI. · Requires insured to be alive on diagnosis date with live medical evidence rather than imposing a 14-day post-diagnosis survival period. | Continuous Cancer Income option cuts cancer relapse/persistence waiting time to 1 year, supporting cash flow during multi-year oncology treatment. · 2-tier ICU triggers provide protection even for severe emergencies or novel illnesses outside named disease definitions. |
| Watch-Outs Before Deciding | From Renewal Age 86 onwards, Multiple Cover and Early Stage benefits terminate automatically (only single Major CI + 5% death cover remain), and premiums step up yearly with age. · If a Major CI claim occurs within the 2-year Early Stage waiting period after an Early Stage payout, the Major payout deducts the earlier 20% advancement. | Annual premiums per HK$1M cover are far higher than pure term CI — do not under-insure your core sum assured just to afford whole-life savings. · Steep early surrender losses apply, and the 10X Multiple CI benefit ends at age 85. |
Sources
- Bowtie Term CI (Early Stage & Multiple Cover) T&Cs PDF (Bowtie Life, Last verified: 2026-11-20)
- Bowtie Term CI (Early Stage & Multiple Cover) Premium Schedule (HK$500k) (Bowtie Life, Last verified: 2026-11-20)
- AIA Hong Kong: On Your Side Insurance Plan 2 Brochure PDF (AIA Hong Kong, Last verified: 2026-11-20)
- AIA Hong Kong: Official Fulfillment Ratio & TCV Ratio Disclosure (AIA Hong Kong, Last verified: 2026-11-20)
CoverHK · Bowtie Term CI (Early & Multiple) vs. AIA On Your Side Plan 2 (Whole-Life Multi-Claim CI)
Want a tailored clause check or exact numbers?
Share your age band, existing corporate medical cover, or current MPF trustee — we will reply in writing with a clear side-by-side summary.