 BOC Life Deferred Annuity (Fixed Term) QDAP: 100% Guaranteed 3.10%–3.30% IRR AuditVS
 AIA Deferred Annuity Plan 2 (Participating QDAP): Guaranteed vs. Projected IRR Audit
BOC Life Fixed-Term QDAP (100% Guaranteed) vs. AIA Deferred Annuity Plan 2: Real IRR Diff
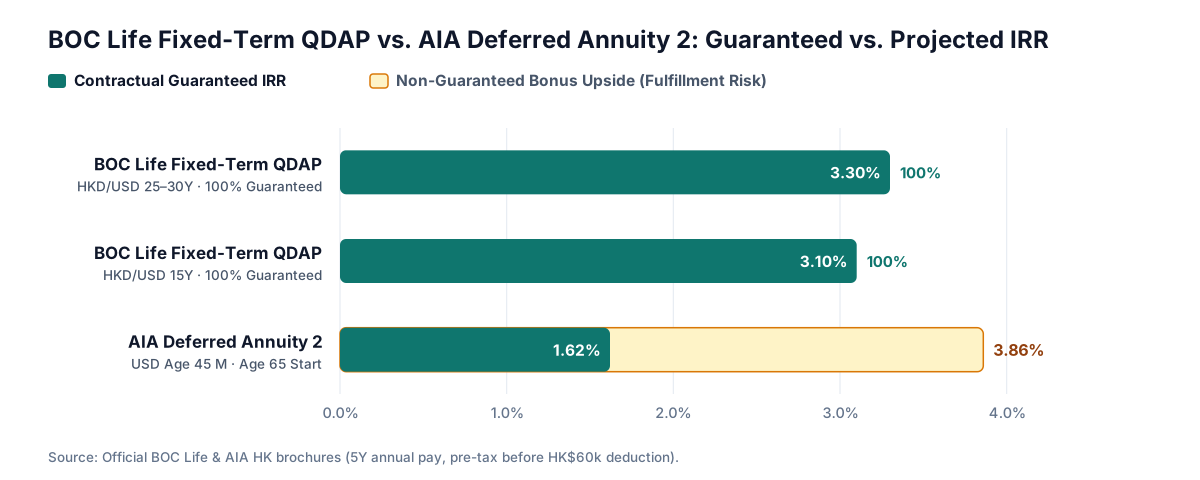
The defining Hong Kong QDAP trade-off: BOC Life's 100%-guaranteed 3.10%–3.30% annualized IRR (HKD/USD annual pay, zero dividend risk) vs. AIA Deferred Annuity Plan 2's 0.10%–2.00% guaranteed / 1.77%–3.87% projected IRR.
Last verified: 2026-11-20 · Official policy wordings and trustee disclosures always prevail.
Key Takeaways
- Guaranteed IRR gap exceeds 1.3%: BOC Life Fixed Term locks in 3.10% (15Y) to 3.30% (25Y–30Y) contractual guaranteed IRR in HKD or USD vs. 0.10%–2.00% guaranteed on AIA Deferred Annuity 2 (age 45 male).
- Dividend trade-off: AIA projects up to 3.87% total IRR only if current non-guaranteed dividend scales hold; at 60%–70% realised fulfillment, net return trails BOC Life's guaranteed floor.
- Currency & flexibility: BOC Life offers native HKD with zero FX spread; AIA adds selectable start ages (50–75) and terminal illness cover in USD.
Visual Comparison
Clause-by-Clause Matrix
Rare 100%-guaranteed Hong Kong QDAP: 5-year premium payment with 10 years of 100% guaranteed monthly annuity income — official brochure lists 3.10% (15Y) to 3.30% (25Y/30Y) annualized guaranteed IRR in HKD or USD with zero dividend fulfillment risk.
Classic participating Hong Kong QDAP contrasting sharply with guaranteed-only annuities: 5/10-year pay with 10-year payout starting ages 50–75; official brochure shows 0.10%–2.00% guaranteed IRR vs. 1.77%–3.87% projected total IRR (age 45 male).
15%–17% bracket taxpayers prioritising contractual guaranteed IRR over volatile non-guaranteed dividend projections.
Taxpayers willing to take dividend fulfillment risk over a 20–30 year horizon in exchange for higher projected upside and flexible payout start ages (50–75).
Payment & Annuity Structure:Fixed 5-year premium payment term with 15/20/25/30-year policy terms (paying 10 years of Guaranteed Monthly Annuity Income starting after the 5th/10th/15th/20th policy anniversary). | Official Annual-Pay Guaranteed IRR at Maturity:Identical in HKD and USD: 3.10% (15Y), 3.20% (20Y), 3.30% (25Y), and 3.30% (30Y) for annual payment (RMB 2.00%–2.38%; non-annual HKD/USD 2.70%–3.25%). | Non-Guaranteed Component & Liquidity Risk:Monthly cash-out annuity stream is 100% guaranteed (only optional accumulation interest is non-guaranteed); subject to BOC Life credit risk and steep early surrender losses.
Official Guaranteed vs. Projected Total IRR (Age 45 NS Male):Start Age 50: Guaranteed 0.10%–0.82% / Projected 1.77%–2.41%; Age 60: 1.27%–1.56% / 3.36%–3.61%; Age 65: 1.39%–1.62% / 3.67%–3.86%; Age 75: 1.84%–2.00% / 3.74%–3.87%. | Official Age-35 Case (5Y Pay, Start Age 65):Total premiums US$37,500; projected maturity payout US$130,797.60 by age 75 with at least 59% guaranteed share of monthly annuity — Guaranteed IRR 2.21% vs. Projected Total IRR 3.87%. | Minimum Premium & Fulfillment Ratio Check:Minimum US$4,800/yr on 5-year pay; because non-guaranteed monthly payouts and terminal dividend drive much of the return, stress-test at 80%/60% fulfillment in CoverHK's IRR Calculator and review AIA's official fulfillment disclosures.
3.10%–3.30% pure guaranteed IRR before factoring in up to HK$10,200/yr salaries tax savings (at 17% marginal rate). · Eliminates dividend fulfillment ratio uncertainty on the monthly annuity stream.
Flexible issue age from 18 with selectable annuity start ages (50/55/60/65/70/75). · Includes Terminal Illness benefit and fee-free option to accumulate monthly annuity payments at interest.
Non-annual payment modes cut guaranteed IRR noticeably (e.g. 2.70%–2.94% on 15Y vs. 3.10% annual); pay annually if cash flow permits. · Shares the HK$60,000 annual deduction cap with MPF TVC — avoid over-allocating beyond unused tax headroom.
Guaranteed IRR (0.10%–2.21%) sits well below BOC Life Fixed Term's 3.10%–3.30% pure guaranteed IRR — if realised dividends land around 60%–80%, net return can trail a guaranteed-only QDAP. · USD-denominated policy introduces FX conversion friction for HKD retirement spending.
| Clause-by-Clause Matrix | BOC Life Deferred Annuity (Fixed Term) QDAP: 100% Guaranteed 3.10%–3.30% IRR Audit | AIA Deferred Annuity Plan 2 (Participating QDAP): Guaranteed vs. Projected IRR Audit |
|---|---|---|
| Overview | Rare 100%-guaranteed Hong Kong QDAP: 5-year premium payment with 10 years of 100% guaranteed monthly annuity income — official brochure lists 3.10% (15Y) to 3.30% (25Y/30Y) annualized guaranteed IRR in HKD or USD with zero dividend fulfillment risk. | Classic participating Hong Kong QDAP contrasting sharply with guaranteed-only annuities: 5/10-year pay with 10-year payout starting ages 50–75; official brochure shows 0.10%–2.00% guaranteed IRR vs. 1.77%–3.87% projected total IRR (age 45 male). |
| Best Suited For | 15%–17% bracket taxpayers prioritising contractual guaranteed IRR over volatile non-guaranteed dividend projections. | Taxpayers willing to take dividend fulfillment risk over a 20–30 year horizon in exchange for higher projected upside and flexible payout start ages (50–75). |
| Verified Clauses & Rates | Payment & Annuity Structure:Fixed 5-year premium payment term with 15/20/25/30-year policy terms (paying 10 years of Guaranteed Monthly Annuity Income starting after the 5th/10th/15th/20th policy anniversary). | Official Annual-Pay Guaranteed IRR at Maturity:Identical in HKD and USD: 3.10% (15Y), 3.20% (20Y), 3.30% (25Y), and 3.30% (30Y) for annual payment (RMB 2.00%–2.38%; non-annual HKD/USD 2.70%–3.25%). | Non-Guaranteed Component & Liquidity Risk:Monthly cash-out annuity stream is 100% guaranteed (only optional accumulation interest is non-guaranteed); subject to BOC Life credit risk and steep early surrender losses. | Official Guaranteed vs. Projected Total IRR (Age 45 NS Male):Start Age 50: Guaranteed 0.10%–0.82% / Projected 1.77%–2.41%; Age 60: 1.27%–1.56% / 3.36%–3.61%; Age 65: 1.39%–1.62% / 3.67%–3.86%; Age 75: 1.84%–2.00% / 3.74%–3.87%. | Official Age-35 Case (5Y Pay, Start Age 65):Total premiums US$37,500; projected maturity payout US$130,797.60 by age 75 with at least 59% guaranteed share of monthly annuity — Guaranteed IRR 2.21% vs. Projected Total IRR 3.87%. | Minimum Premium & Fulfillment Ratio Check:Minimum US$4,800/yr on 5-year pay; because non-guaranteed monthly payouts and terminal dividend drive much of the return, stress-test at 80%/60% fulfillment in CoverHK's IRR Calculator and review AIA's official fulfillment disclosures. |
| Strengths | 3.10%–3.30% pure guaranteed IRR before factoring in up to HK$10,200/yr salaries tax savings (at 17% marginal rate). · Eliminates dividend fulfillment ratio uncertainty on the monthly annuity stream. | Flexible issue age from 18 with selectable annuity start ages (50/55/60/65/70/75). · Includes Terminal Illness benefit and fee-free option to accumulate monthly annuity payments at interest. |
| Watch-Outs Before Deciding | Non-annual payment modes cut guaranteed IRR noticeably (e.g. 2.70%–2.94% on 15Y vs. 3.10% annual); pay annually if cash flow permits. · Shares the HK$60,000 annual deduction cap with MPF TVC — avoid over-allocating beyond unused tax headroom. | Guaranteed IRR (0.10%–2.21%) sits well below BOC Life Fixed Term's 3.10%–3.30% pure guaranteed IRR — if realised dividends land around 60%–80%, net return can trail a guaranteed-only QDAP. · USD-denominated policy introduces FX conversion friction for HKD retirement spending. |
Sources
- BOC Life: Deferred Annuity (Fixed Term) Official Product Brochure PDF (BOC Life, Last verified: 2026-11-20)
- AIA Hong Kong: AIA Deferred Annuity Plan 2 Brochure PDF (AIA Hong Kong, Last verified: 2026-11-20)
- AIA Hong Kong: Official Fulfillment Ratio & TCV Ratio Disclosure (AIA Hong Kong, Last verified: 2026-11-20)
CoverHK · BOC Life Fixed-Term QDAP (100% Guaranteed) vs. AIA Deferred Annuity Plan 2: Real IRR Diff
Want a tailored clause check or exact numbers?
Share your age band, existing corporate medical cover, or current MPF trustee — we will reply in writing with a clear side-by-side summary.